December 31 is not just the end of the calendar year; it is a hard deadline for a surprising number of financial decisions. Tax-loss harvesting, retirement contributions, and required minimum distributions all must be completed before the year ends, or the opportunity is gone until next year. Below are nine moves worth reviewing now, while there is still time to act.
1. Should I Harvest Tax Losses This Year?
Tax-loss harvesting means selling investments that have declined in value to offset capital gains elsewhere in your portfolio. The strategy can help manage your tax liability, but it requires careful coordination. The wash-sale rule generally disallows a loss if you buy the same or a “substantially identical” investment within 30 days before or after the sale.
At Arbor, tax-loss harvesting isn’t a once-a-year exercise. We monitor portfolios throughout the year so opportunities can be evaluated as they arise, rather than waiting for a year-end scramble. Whether harvesting a particular loss makes sense is a case-by-case decision, weighed against your full investment and tax picture, including your current and expected capital gains, income, and investment objective. We also coordinate carefully around the wash-sale rule, which can apply across accounts held by both spouses and may include IRA transactions.
2. Is My Portfolio Still Aligned with My Goals?
Markets move, and not all asset classes move together. Over time, your portfolio can drift from its intended allocation, potentially leaving you with more or less risk than you originally intended. Rebalancing brings the portfolio back to its target allocation by trimming positions that have grown beyond their target and adding to positions that have fallen below it.
At Arbor, rebalancing is threshold-based rather than tied to the calendar. When an asset class drifts meaningfully enough from its target, we evaluate whether rebalancing makes sense based on your overall portfolio, tax situation, and current goals. Tax loss harvesting and rebalancing are separate decisions, each considered when appropriate rather than automatically bundled together.
3. Am I Contributing Enough to My Retirement Accounts?
401(k) contributions generally must be made by the end of the calendar year, while IRA contributions generally have until the tax-filing deadline the following spring. For 2026, the 401(k) limit is $24,500, with an additional $8,000 catch-up for those 50 and older ($11,250 for ages 60–63). The IRA limit is $7,500, plus a $1,100 catch-up for those 50 and older.
A common misstep we see is overlooking one or more retirement savings opportunities available to you. Through our financial planning process, we help clients evaluate their options, both within employer-sponsored plans and outside of them, and determine how much to save and where. We then help build and implement a tax-aware savings strategy that considers current cash flow, tax circumstances, and long-term goals.
4. Does a Roth Conversion Make Sense This Year?
Converting funds from a traditional retirement account to a Roth means paying income tax now in exchange for the potential for tax-free growth and withdrawals later. A conversion may be particularly worth considering during a lower-income year, during the gap between retirement and the start of Social Security or RMDs, or following a market decline when the tax cost of converting may be lower. Regardless, Roth conversions are not a one-size-fits-all move.
When we discuss a Roth conversion with a client, we consider both the tax cost today and the potential benefit in the future. We look at the client’s current and projected tax brackets, cash flow, retirement needs, and whether the assets may ultimately be passed on to loved ones. A Roth conversion is not the right move for everyone; the decision should be driven by the client’s goals and how the conversion fits into the broader financial plan.
5. Do I Need to Take a Required Minimum Distribution?
Required minimum distributions (RMDs) currently begin at age 73. Missing one, or taking less than required, triggers a penalty of up to 25% of the shortfall (potentially reduced to 10% if corrected quickly). A qualified charitable distribution can satisfy some or all of the RMD without adding to taxable income.
Once you reach age 73, the IRS requires you to withdraw a minimum amount from most tax-deferred retirement accounts each year, generally by December 31. The amount is based on your account balance and the IRA life-expectancy tables. RMDs are generally taxable income, so thoughtful planning can help manage their impact on your overall tax picture.
For clients who are charitably inclined, we discuss qualified charitable distributions (QCDs) proactively. Beginning at age 70 ½, eligible individuals can transfer funds directly from an IRA to a qualified charity. A QCD can satisfy some or all of your RMD while keeping the amount transferred out of taxable income entirely. For those already giving to charity, this can be an effective way to support causes that are important to you while managing taxable income.
6. Have I Used My Annual Gift Exclusion?
In 2026, you can give up to $19,000 per recipient to as many people as you like, without touching your lifetime gift and estate tax exemption or filing a gift tax return. The exclusion does not carry forward, so if you don’t use this year’s amount, it is gone. For families considering gifts to children or grandchildren, using the annual exclusion amount can be a simple way to transfer wealth over time and potentially remove future appreciation from your estate.
Year-end gifting can take many forms, and the right approach depends on your goals and circumstances. In an upcoming Arbor Insights article, we’ll take a deeper look at year-end giving, including annual exclusion gifts, charitable giving, donor-advised funds, appreciated securities, and qualified charitable distributions.
7. Am I About to Lose Unused HSA or FSA Funds?
FSA funds are typically subject to a use-it-or-lose-it rule, although some plans allow a limited carryover or grace period. Check your plan’s specific deadlines and rules before year-end so you don’t forfeit funds unnecessarily. HSAs work differently: unused funds roll over indefinitely and remain yours even if you change jobs or health plans. For 2026, HSA contribution limits are $4,400 for self-only coverage and $8,750 for family coverage, plus a $1,000 catch-up contribution for those 55 and older.
An HSA can be a valuable long-term planning tool because funds can be invested and used tax-free for qualified medical expenses. For clients who have the cash flow to do so, we may discuss paying current healthcare costs out of pocket and allowing HSA assets to grow for future healthcare needs. Given the significant and often unpredictable cost of healthcare later in life, an HSA can serve as an important part of a broader retirement plan.
8. When Did I Last Review My Beneficiary Designations?
Beneficiary designations on retirement accounts, life insurance, and annuities generally determine who receives those assets, regardless of what your will says. Life changes – a marriage, divorce, birth or death in the family, or even a job change – can make an outdated designation inconsistent with your wishes. It is important to review both primary and contingent beneficiaries periodically to make sure they still reflect your intentions.
For IRAs we manage, we maintain beneficiary designations on file and review them as part of our ongoing relationship. We also encourage clients to review beneficiary designations on 401(k)s and other accounts held outside of Arbor. Often the issue isn’t an intentional decision but simply a designation that was never updated. We help identify these gaps and bring them to your attention. Beneficiary planning can also provide an opportunity to support a charity or other organization that is meaningful to you.
9. Can I Still Influence My Tax Bill This Year?
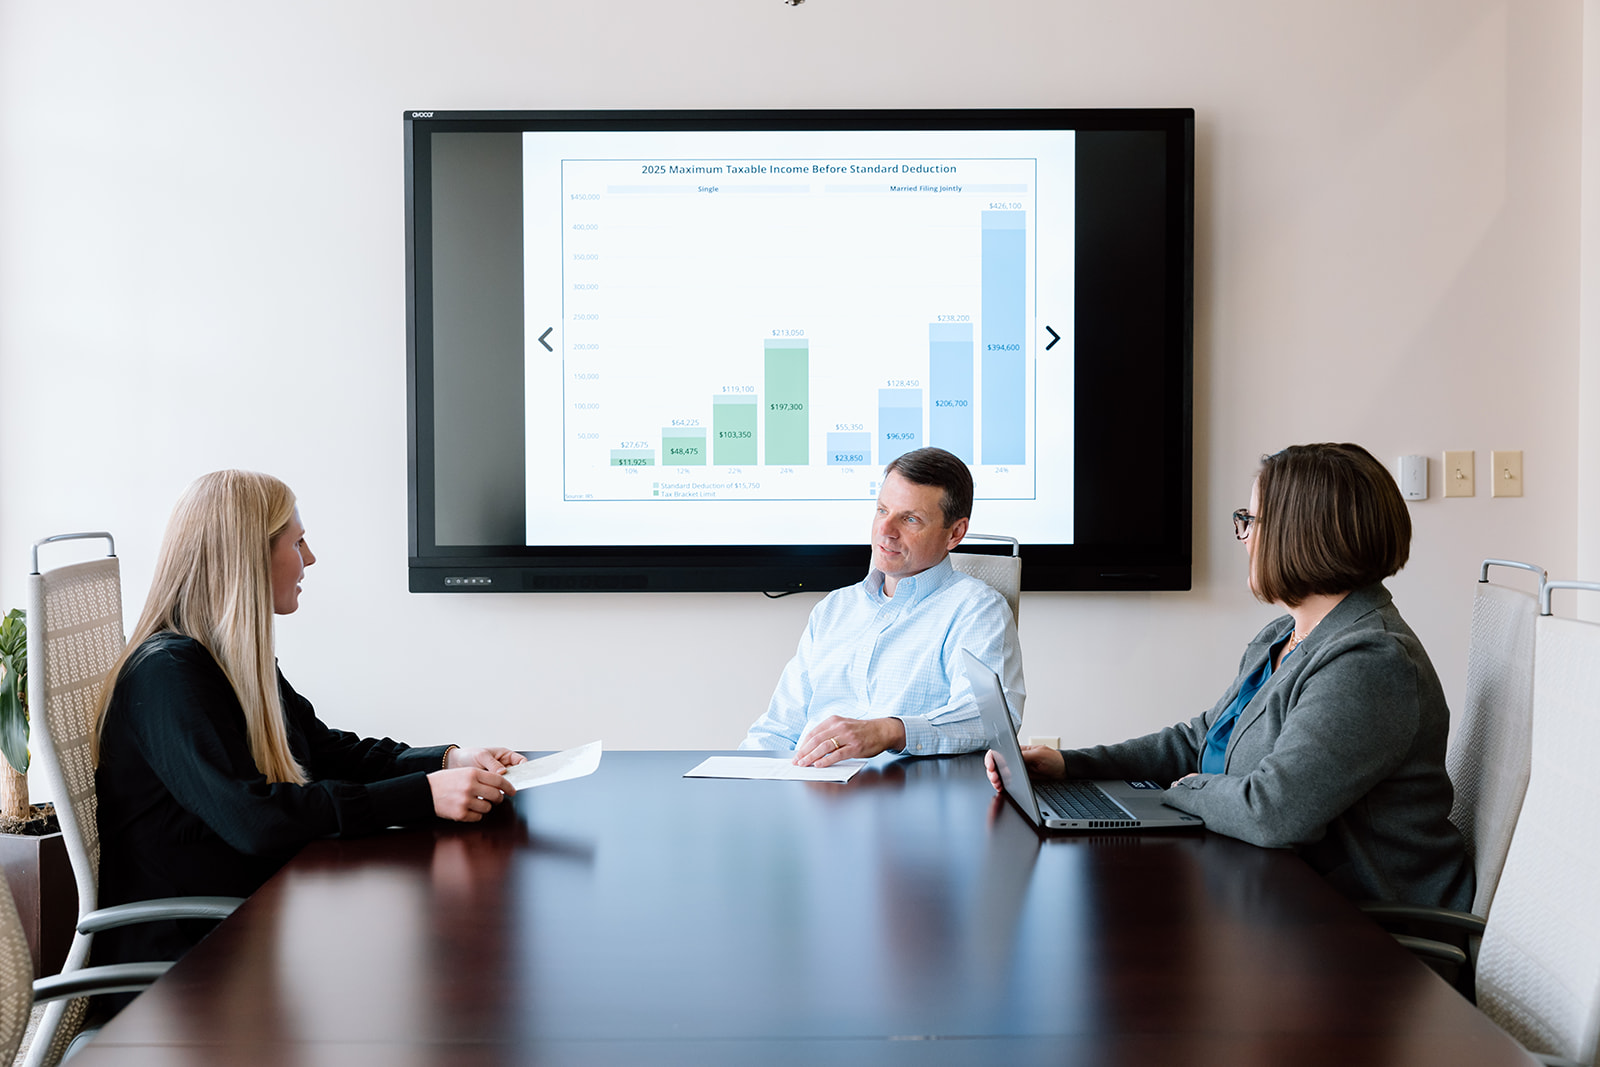
The timing of income and deductions is one of the last planning opportunities available before year-end. Depending on your circumstances, decisions about when income is recognized and when deductions are taken may affect your taxable income for the year. This can include timing of a bonus, charitable contributions, or other deductible expenses.
At Arbor, we consider the tax implications of these decisions as part of your broader financial plan. We are not CPAs, but we are tax-aware and work directly alongside your CPA rather than in place of them. With your permission, we regularly communicate directly with our clients’ CPAs, particularly when coordinating such items as Roth conversions, charitable giving, and quarterly estimated tax payments, to help ensure your financial and tax strategies are working together.
Closing
Each of these moves is manageable on their own, but they interact with one another, and with your broader financial plan, in ways that are easy to miss without a second set of eyes.
A tax-loss harvest can affect Roth conversion. A QCD can change how a beneficiary review plays out. Retirement contributions and income timing can both impact your tax bracket. None of these moves should be made in a vacuum.
At Arbor Investment Advisors, we believe year-end planning works best as a coordinated conversation, not a checklist completed alone. If any of these are things you haven’t addressed yet, give us a call. We’re happy to help you determine what deserves attention before the year ends.